BLOG, CAR FINANCE
Car Finance Requirements South Africa: A Complete Guide
Car Finance Requirements in South Africa: What You Need to Qualify
Applying for car finance can feel overwhelming if you are not sure what documents you need or what lenders are looking for. The good news is that preparing in advance can make the process much easier.
While requirements can differ between lenders and individual applicants, vehicle-finance applications in South Africa generally involve information about your identity, income, banking history, address, existing financial commitments and ability to afford the proposed repayment.
In this guide, we explain the common car finance requirements in South Africa, what documents you may need and how you can prepare before submitting an application.
What Are the Basic Requirements for Car Finance?
The exact requirements depend on the lender and your personal circumstances, but you will generally need to provide documents that allow the credit provider to verify who you are, where you live and what you earn.
Common documents may include:
- South African identity document or other accepted identification
- Valid driver’s licence
- Proof of residential address
- Recent bank statements
- Proof of income
- Recent payslips, where applicable
- Information about existing financial commitments
For example, WesBank’s current vehicle-finance information confirms that applicants may need to submit supporting documentation after completing an application. Requirements can vary depending on the applicant and finance application.
Why Do Lenders Ask for Bank Statements?
Your bank statements can provide a picture of how money moves through your account.
They can help demonstrate income deposits, regular expenses, existing debit orders and other financial commitments.
This is particularly important when assessing whether a proposed vehicle repayment is realistically affordable.
The National Credit Act affordability framework requires credit providers to consider a consumer’s financial position when assessing credit.
The South African affordability assessment regulations require consideration of factors including income, debt obligations, maintenance obligations and necessary expenses.
This means your bank statements are not simply paperwork. They can help demonstrate your actual financial position.
Proof of Income Is an Important Part of Your Application
A lender needs to establish whether you have sufficient income to meet the proposed repayment together with your other financial commitments.
If you are formally employed, your recent payslips may be used as part of the income-verification process.
If you are self-employed, a business owner, a freelancer or earn income from another source, the documentation required may be different.
The important thing is to provide accurate and verifiable information rather than trying to make your income appear larger than it really is.
South African affordability guidance also recognizes that consumers may have different types of income and that appropriate verification may be required depending on the circumstances.
How Much Income Do You Need to Qualify for Car Finance?
This is one of the questions we hear most often: “How much must I earn to qualify for a car?”
There is no single salary amount that guarantees approval for every applicant.
A person earning R30,000 per month may have very different affordability from another person earning the same amount.
Why?
- They may have different rent or bond payments.
- They may have different household expenses.
- They may have different credit repayments.
- They may have different family or maintenance obligations.
- They may have different credit histories.
- They may be looking at completely different vehicle prices.
This is why affordability is about much more than your salary.
Credit History Can Affect Your Application
Your credit history can form part of the lender’s assessment when you apply for traditional vehicle finance.
Your repayment history and existing credit obligations can provide information about how you have managed credit in the past.
The National Credit Act establishes a framework for responsible credit granting and consumer protection in South Africa.
The affordability regulations also require consideration of a consumer’s debt repayment history when conducting an affordability assessment.
This is one reason it is important to keep your existing accounts up to date and understand your credit commitments before applying for additional finance.
What If You Are Self-Employed?
Being self-employed does not automatically mean you cannot apply for vehicle finance.
However, proving income can sometimes be more complicated when you do not receive a traditional monthly payslip.
If you are self-employed, you may need additional documentation to demonstrate the income generated by your business and your ability to meet the proposed repayment.
Keep your business and personal financial records organized and make sure your bank statements clearly reflect your legitimate income.
Never create artificial transactions or provide inaccurate information simply to improve your application. An affordability assessment is designed to determine whether the proposed credit is genuinely sustainable.
Why Your Monthly Expenses Matter
Your income is only one side of the affordability equation.
Your regular expenses and existing financial obligations also matter.
Before applying for vehicle finance, make a list of:
- Rent or bond payments
- Groceries and household expenses
- Electricity and water
- Insurance
- Existing loan repayments
- Credit-card payments
- Store accounts
- School or childcare costs
- Maintenance obligations
- Transport expenses
- Other recurring commitments
Once you understand your current commitments, you can make a more realistic decision about the vehicle you can afford.
Don’t Choose the Car Before Checking Your Budget
One of the most common mistakes buyers make is choosing their dream vehicle first and trying to make the finances work afterwards.
A better approach is to determine your affordability first.
Once you know what monthly commitment is realistic, you can start looking at vehicles within that range.
Remember that the finance repayment is not the complete cost of owning a car.
Also consider:
- Insurance
- Fuel
- Vehicle maintenance
- Tyres
- Licensing costs
- Tracking, where applicable
- Unexpected repairs
What Documents Should You Have Ready?
Preparing your documentation before you apply can make the process much smoother.
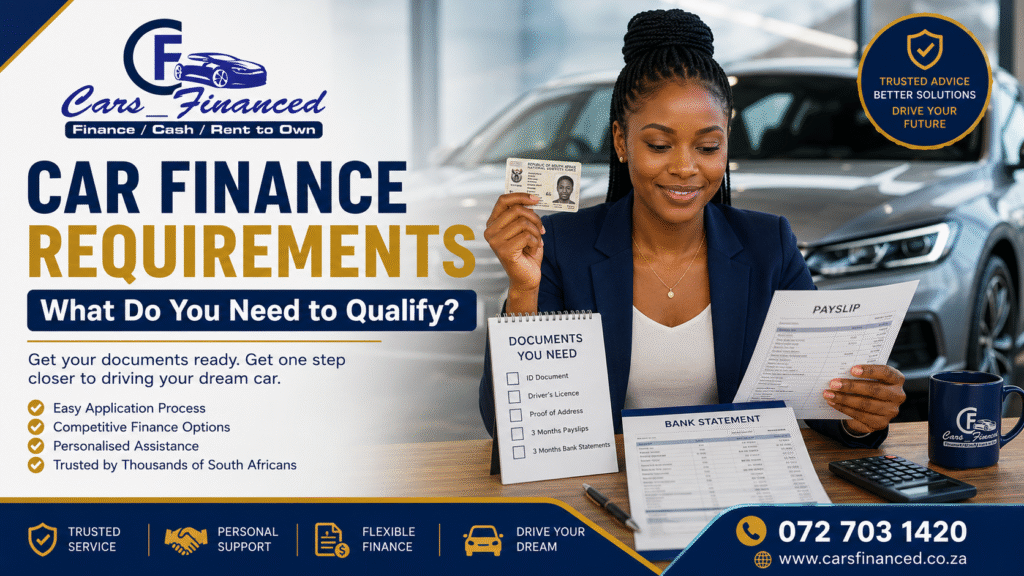
At Cars Financed, we recommend having the following documents ready for assistance:
- Three months of payslips
- Three months of bank statements
- ID and driver’s licence
- Proof of address
These are the documents currently listed by Cars Financed for customers seeking assistance with vehicle finance.
However, individual lenders may request additional documentation depending on your employment status, income, credit profile and the type of application.
You can learn more about Cars Financed and our vehicle-finance services on our About Cars Financed page.
What Happens After You Submit Your Documents?
Once your documents have been submitted, the relevant finance provider will assess your application.
The assessment can consider your income, expenses, existing credit obligations, repayment history and other relevant criteria.
The result can be an approval, a request for additional information, or a decline.
It is important to understand that having all the required documents does not guarantee approval.
Documents simply allow the relevant credit provider to assess your application.
What If Your Car Finance Application Is Declined?
A declined application does not necessarily mean that you will never be able to own a car.
The first step is to understand why the application was declined.
Possible reasons can include:
- Insufficient affordability
- High existing debt commitments
- Adverse credit history
- Insufficient or inconsistent income evidence
- The vehicle being outside your affordability range
- Other lender-specific risk criteria
If traditional bank finance is not suitable for your circumstances, there may be alternative vehicle ownership routes worth investigating.
Cars Financed also assists clients with rent-to-own vehicle options where appropriate.
How Cars Financed Can Help
At Cars Financed, our goal is to help customers understand their vehicle-finance options and find a solution that fits their circumstances and budget.
We work with different vehicle-purchase routes, including:
- Traditional vehicle finance through major banks
- Rent-to-own solutions
- Cash vehicle purchases
You can also read our guide on how to qualify for car finance in South Africa for more information about the application process.
We believe informed customers make better decisions. Understanding your documents, affordability and finance options before you commit can help you approach the vehicle-buying process with greater confidence.
Car Finance Application Checklist
Before applying, use this simple checklist:
- Check your monthly income.
- List your existing expenses and debt repayments.
- Review your credit profile where appropriate.
- Choose a realistic vehicle budget.
- Gather your identification documents.
- Prepare recent bank statements.
- Prepare proof of income.
- Prepare proof of address.
- Understand the full cost of owning the vehicle.
- Read and understand the finance agreement before signing.
Taking these steps before applying can help you approach the process in a more informed and organized way.
Frequently Asked Questions About Car Finance Requirements
What documents do I need for car finance in South Africa?
Common documents include identification, a valid driver’s licence, proof of address, recent bank statements and proof of income. Specific requirements vary between lenders and applicants.
Do I need three months of bank statements?
Many vehicle-finance applications request recent bank statements. Cars Financed currently asks customers to have three months of bank statements available when seeking assistance. Individual lenders may have their own requirements.
Do I need payslips to apply for car finance?
Salaried applicants are commonly asked for proof of income such as payslips. If you are self-employed or earn income in another way, alternative or additional income verification may be required.
Can I get car finance if I am self-employed?
Yes. Self-employed people can apply for vehicle finance. The lender may require additional documentation to verify income and affordability.
Does having all the required documents guarantee approval?
No. Documents allow the lender to assess your application, but approval depends on affordability, credit history and the lender’s other criteria.
Can I apply for car finance if I have existing debt?
You may still apply, but your existing debt obligations will form part of the affordability assessment. Providing complete and accurate information is important.
What happens if my application is declined?
Find out why the application was declined and consider whether the issue relates to affordability, existing commitments, credit history, income verification or the vehicle selected. Depending on your circumstances, alternative vehicle-purchase options may also be worth exploring.
Ready to Explore Your Vehicle-Finance Options?
Getting your documents ready is only the first step. The next step is understanding what vehicle and finance option makes sense for your circumstances.
At Cars Financed, we help customers navigate the vehicle-finance process and explore available options.
Ready to get started?
Visit Cars Financed and start your vehicle-finance journey →
Authoritative Resources